

The Apprenticeship Levy has undergone its biggest overhaul since its introduction, with major changes taking effect from 1 August 2026. For Small to Medium-sized Enterprises (SMEs), the most significant development is the expansion of what levy funds can be used for under the new Growth and Skills Levy. This expansion comes alongside tighter funding rules, making planning more important than ever.
The two headline changes are the removal of the government top-up and that levy-paying employers can now use their funds for a broader range of approved training, not just traditional apprenticeships.
Alongside full apprenticeships, the Growth and Skills Levy can now support foundation apprenticeships and approved apprenticeship units. This gives businesses greater flexibility to address specific skills gaps, upskill employees more quickly and access shorter, targeted training programmes without committing staff to a full apprenticeship.
Funding changes
The funding changes also create new financial pressures. From 1 August 2026, the government has removed the 10% top-up that was previously added to levy funds entering employers' apprenticeship service accounts.
Businesses will see less funding available.
There is also a reduction in the expiry period for new levy funds. Previously, employers had 24 months to spend funds before they expired. Any levy funds entering accounts from 1 August 2026 must now be used within 12 months. Funds already in accounts before that date continue to benefit from the old 24-month rule.
For businesses, this means unused funds are far more likely to be lost if training plans are delayed, pushing employers to regularly review their balances and plan training around the funding available.
Changes have also been made to co-investment arrangements when levy-paying employers exhaust their available funds.
For apprentices aged 16 to 24, eligible training costs are fully funded by government once levy funds are depleted. For apprentices aged 25 and over, employers must contribute 25% of the training cost, with government funding the remaining 75%, up to the relevant funding band limit.
This represents a higher contribution requirement than many employers were previously accustomed to and could increase training costs for businesses with older apprentices.
The levy itself remains unchanged. Employers with annual pay bills exceeding £3 million must pay 0.5% of their payroll costs, less a £15,000 annual allowance. The levy is collected through PAYE and applies to private, public and voluntary sector organisations. Connected companies and charities must consider their combined pay bill when determining liability.
In England, levy-paying employers access funds through an apprenticeship service account. The amount available is based on the levy paid and the proportion of employees who live in England. These funds can be used to pay for approved training and assessment costs, subject to funding band limits.
Non-levy paying businesses
For SMEs that do not pay the levy, government support remains. From August 2026, non-levy employers receive 100% funding for apprentices aged 16 to 24, up to the funding band maximum. For apprentices aged 25 or over, employers contribute just 5%, with the government paying the remaining 95%.
Eligible non-levy employers may also qualify for a hiring incentive of up to £2,000 when recruiting a new apprentice aged 16 to 24 from October 2026.
Levy funds can pay for approved training, assessment, off-the-job learning, certain qualifications and English and maths provision linked to apprenticeship programmes. They cannot be used for wages, recruitment costs, travel expenses, general business overheads or equipment required for normal job duties. Any training costs above the funding band maximum must be paid directly by the employer.
- Another opportunity for SMEs is the levy transfer. Larger levy-paying employers can transfer up to 50% of their previous year's levy funds to other organisations, including smaller businesses within supply chains or local communities. This can provide valuable access to funded training where SMEs might otherwise face costs.

The Chancellor, John Healey, has given a number of speeches explaining how he intends to boost growth, reduce red tape and maintain fiscal responsibility.
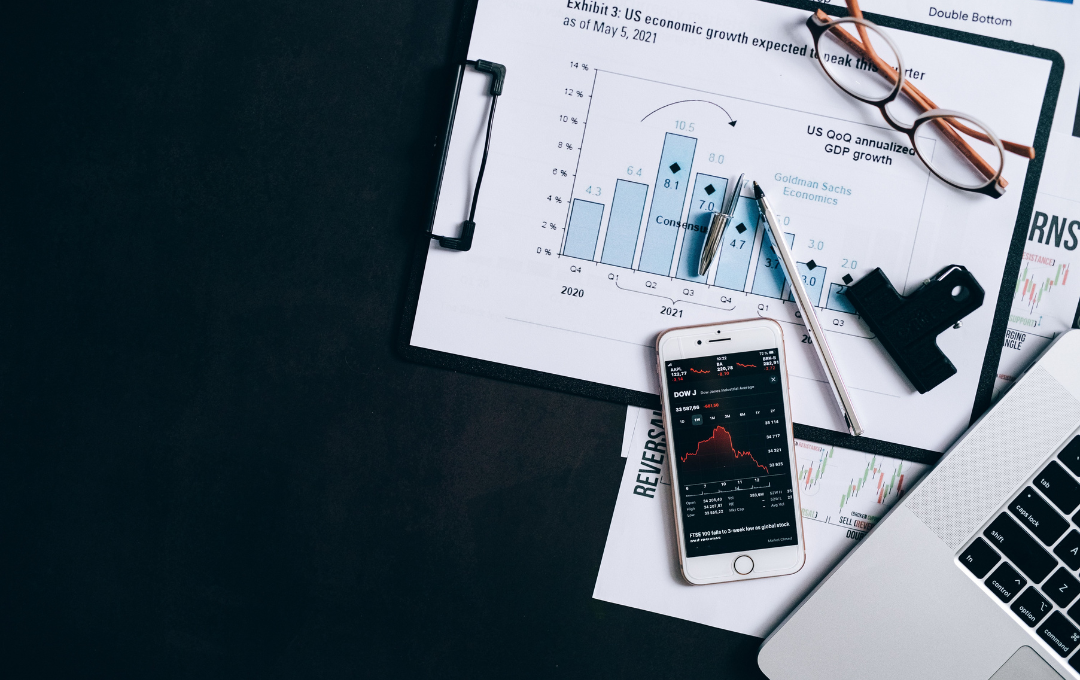
The latest Mergers and Acquisitions (M&A) data from the Office for National Statistics (ONS) reveal a depressing landscape for UK companies. Foreign acquisitions of UK companies soared in value to £25.4 billion, up £9.7 billion from Q1 2026 and £15.7 billion higher than Q2 2025, highlighting how cheap UK company valuations are compared to foreign markets.